Storm resources
How a roof insurance claim actually works
A hail claim is not complicated, but it happens in a fixed order and each step belongs to someone. Knowing whose move it is saves weeks of waiting and most of the frustration.
Who does what
- You hold the policy, file the claim and make every decision about it.
- Your insurance company sends an adjuster, decides what is covered and pays.
- A roofing contractor inspects, documents and does the work. In Texas a contractor may not act as a public adjuster on a job it is also doing the work on (Texas Insurance Code section 4102.163), so a roofer cannot negotiate your claim for you.
- A public adjuster, licensed by the Texas Department of Insurance, is someone you can hire yourself to negotiate a claim, for a fee.
1. Document the damage
Photos first, ideally the same day. The photo checklist covers what to capture. A contractor's inspection adds close-up photos of each slope that you cannot take from the ground.
2. Report it to your insurer
Call your agent or insurance company as soon as you can. Your policy sets how long you have to report storm damage, and many Texas policies ask for notice within about a year of the storm. Do not wait for the last month: damage gets harder to tie to one storm the longer it sits.
Texas prompt-payment rules (Insurance Code chapter 542) put deadlines on the insurer too. In general it must acknowledge your claim and start its investigation within 15 days, decide within 15 business days of receiving everything it asked for (it can take up to 45 more days if it explains why), and pay within 5 business days of agreeing.
3. The adjuster's inspection
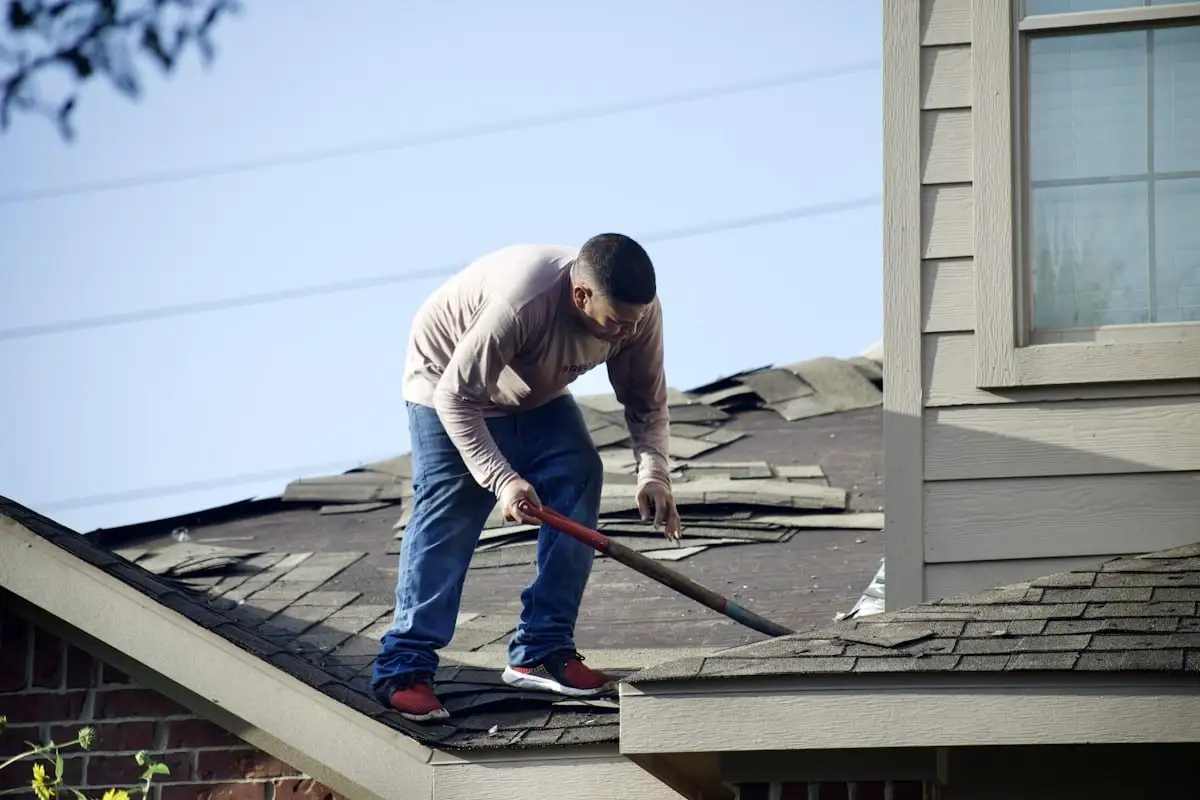
The insurer sends an adjuster to inspect the roof. You can ask your contractor to be there to point out the damage they documented. The adjuster works for the insurance company and writes the estimate the claim is paid on.
4. Reading the estimate
- Replacement cost is what it costs to replace the roof new.
- Actual cash value is replacement cost minus depreciation for the roof's age.
- On many replacement-cost policies, the first check is the actual cash value, and the held-back depreciation is paid once the work is finished and the final invoice is sent.
- Your deductible is subtracted. It is yours to pay, and in Texas no contractor may offer to cover it. See what Texas law says.
- If you have a mortgage, the lender may be named on the check alongside you.
5. If the numbers look wrong
Compare the adjuster's report with a contractor's written estimate line by line. If something was missed, ask the insurer for a re-inspection and send your photos and measurements. Many policies also include an appraisal clause for disputes over the amount. If you believe the claim is being handled unfairly, the Texas Department of Insurance takes complaints at 800-252-3439.
6. The work and the final invoice
Once you approve a written scope, the work is scheduled. After it is done, the contractor's final invoice goes to the insurer so any held-back depreciation can be released. Keep proof that you paid your deductible: the insurer may ask for it.
General information about how roof claims usually work in Texas, written for a demo site. It is not legal or insurance advice. Your policy and your insurer decide what is covered.